

My rent was due in three days and I was $200 short. I had heard people mention a “cash app loan” before but never actually looked into it — I assumed it was something complicated, like applying for a personal loan at a bank with paperwork and a credit check.
It was not. I opened my Cash App, tapped the Banking tab, and there it was — Borrow. My available offer was $150. Not quite enough on its own, but combined with what I already had, it covered me. The fee was simple, the terms were displayed clearly before I accepted anything, and the money was in my balance within seconds.
That experience is what this guide is built around. A cash app loan — officially called Cash App Borrow — is a small, short-term loan feature built directly into the app. It is not available to every account, the maximum amount is lower than a lot of websites claim, and understanding exactly how it works before you need it is the difference between using it well and getting caught off guard by a fee or a late repayment.
This guide covers everything: limits, fees, APR, repayment terms, eligibility, and what to do if Cash App says no.
“Disclosure: This article contains affiliate links. I may earn a small commission at no extra cost to you if you sign up through my links. This helps support my work and allows me to provide helpful, honest guides.”
My $200 Rent Shortfall — Why I Looked Into Cash App Loan
I want to be specific about this story because the small details are what actually matter when you are deciding whether to trust a financial feature like this.
I had been using Cash App for about five months — mostly for splitting bills with roommates and receiving freelance payments. I had set up direct deposit for one client about two months earlier, almost by accident, because it was the easiest way for them to pay me.
When I opened the Borrow section that day, I did not know what to expect. What I found was a clear screen: my available amount ($150), the exact fee ($7.50), the total I would owe ($157.50), and the date it was due (four weeks out). No hidden steps, no phone call, no waiting period.
I accepted, used the money, and repaid it nine days later when my freelance payment came in — well before the deadline. The fee stayed the same regardless of repaying early; that surprised me at first, but it made sense once I understood it is a flat fee, not daily interest.
That straightforward experience is exactly why I think a clear-eyed guide to the cash app loan feature is useful — it works well, but only if you understand the mechanics before you are in a rush.
What Is a Cash App Loan?
A “cash app loan” is the common way people refer to Cash App Borrow — a short-term loan feature built directly into the Cash App, developed by Block, Inc. It is not a separate loan application or a third-party lending product you search for. It appears (for eligible users) inside the app itself.
The Basics
- Loan amount: A small amount, typically $20 to $400 for most users
- Funding: Instant to your Cash App balance once you accept the offer
- Fee: A flat 5% fee on whatever amount you borrow — not daily or monthly interest
- Repayment: Due in full four weeks after you borrow
- No credit check: Eligibility is based on your Cash App account activity, not your credit score
Who Actually Lends the Money
Cash App itself is a financial technology platform, not a chartered bank. The actual loan is issued and underwritten through a regulated bank partner that works with Block, Inc. The specific partner bank named in your loan agreement can vary, so always check the agreement displayed in your app at the time you borrow — this is the only fully accurate source for your specific loan.

Cash App Loan No Credit Check — How Eligibility Really Works
One of the most appealing things about a cash app loan is that there is no credit check involved. But “no credit check” does not mean “everyone qualifies automatically.” Eligibility works differently.
What Cash App Actually Looks At
Based on consistently reported factors across user experiences and financial review sources, eligibility tends to depend on:
| Factor | Why It Matters |
|---|---|
| Direct deposit history | The single strongest signal of eligibility |
| Account age | Newer accounts (under 30–60 days) rarely qualify |
| Regular Cash Card use | Shows consistent, active account engagement |
| Positive account balance habits | Accounts that sit at $0 constantly are less likely to qualify |
| Account standing | No disputes, fraud flags, or policy violations |
| State of residence | Available in most, but not all, US states |
| Age | Must be 18 or older |
What Does NOT Matter
- Your credit score (Experian, Equifax, or TransUnion)
- Your employment status
- Your income level, specifically
- How long you’ve had a bank account elsewhere
This is genuinely one of the only loan-like products available where your credit history plays no role — which is also exactly why it should not be treated as a substitute for building credit. The CFPB at consumerfinance.gov has helpful resources on how credit-building and short-term borrowing serve different financial goals.
What Is the Limit on Cash App Loan?
This is one of the most searched — and most misunderstood — questions about the cash app loan feature, so let’s be precise.
The Honest Range
Based on currently available information, most users see a maximum cash app loan limit somewhere between $20 and $400. Some accounts with stronger activity history, consistent direct deposits, and (in some cases) an active paid subscription tier may see limits closer to $500, though Cash App has not published an official, permanent ceiling that applies universally to every account.
First-time borrowers commonly report an initial offer in the $20–$150 range rather than starting near the maximum.
Can You Borrow $1,000 From Cash App?
No. Despite some claims circulating online, there is no confirmed, official version of Cash App Borrow that offers $1,000. The realistic top end reported across multiple independent reviews is $400–$500. If you see a website or ad claiming a guaranteed $1,000 Cash App loan, treat it with serious skepticism — it is not consistent with how the official feature works.
How Your Limit Can Change Over Time
- Repaying on time, consistently, tends to gradually increase your offered amount
- Late repayment can lower your limit or temporarily remove access
- There is no manual “request an increase” button — the limit is generated by Cash App’s internal review of your account
Cash App Loan Interest Rate and APR Explained
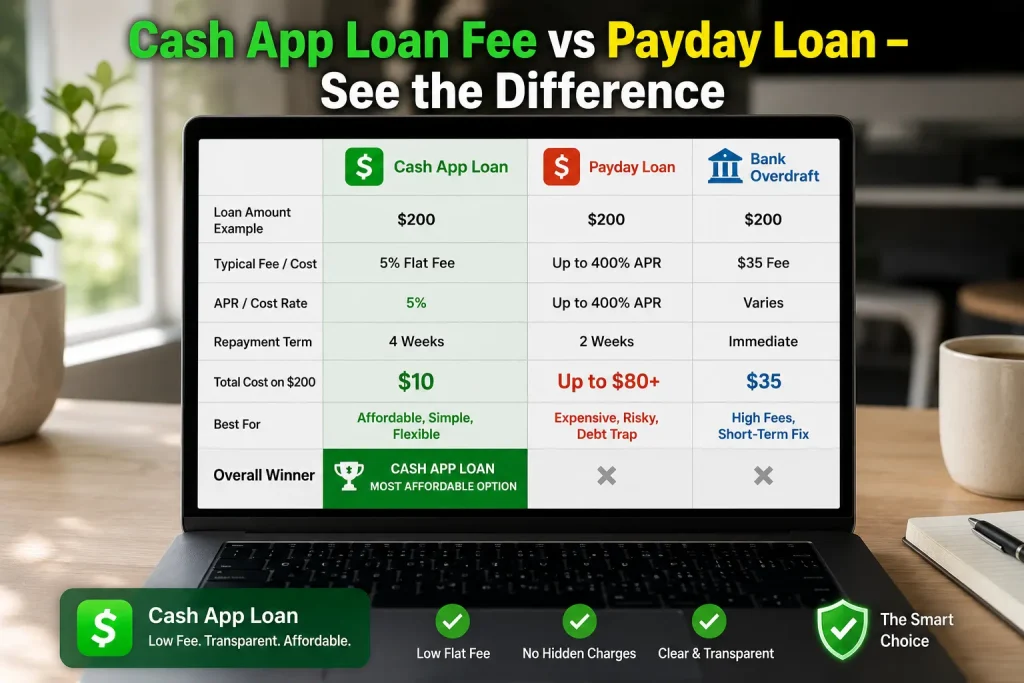
People often ask about the “interest rate,” but Cash App Borrow does not technically charge interest the way a credit card or personal loan does. It charges a flat fee. Understanding the APR equivalent, though, helps you compare it fairly to other options.
The Fee Structure
- 5% flat fee on the amount borrowed, charged once, regardless of how quickly you repay
- 1.25% per week late fee if you do not repay by the due date
What That Works Out to as an APR
Because the loan term is short (four weeks) and the fee is flat, the annualized APR equivalent works out to roughly 60–65% when calculated the way the Truth in Lending Act requires lenders to disclose. Cash App is required to show this APR figure to you directly in the app before you accept any loan — always read that disclosure.
How That Compares
| Borrowing Option | Approximate APR |
|---|---|
| Cash App loan | ~60–65% |
| Credit card cash advance | 25–30% |
| Personal loan (good credit) | 6–12% |
| Personal loan (fair credit) | 15–29% |
| Payday loan | 300–400%+ |
| Bank overdraft (per-incident, annualized) | Often 300%+ equivalent |
A cash app loan is expensive compared to traditional credit — but considerably cheaper than a payday loan or a bank overdraft fee for a similarly small, short-term amount.
Cash App Loan Repayment Terms
Understanding cash app loan repayment terms before you borrow prevents almost every problem people run into with this feature.
The Standard Terms
- Repayment period: 4 weeks from the date you accept the loan
- Repayment method: Automatically deducted from your Cash App balance on the due date
- Backup method: May attempt to pull from a linked bank account if your Cash App balance is insufficient
- Early repayment: Allowed anytime, with no reduction in the flat fee already charged
- Grace period: A short window after the due date before late fees apply (confirm the exact window in your specific loan agreement, as it can vary)
What Happens After the Due Date
If your balance cannot cover the repayment on the due date:
- A 1.25% weekly late fee begins accruing on the outstanding amount
- Your eligibility for future borrowing may be reduced or paused
- Cash App may continue attempting to collect from your balance or linked bank account until the loan is repaid

Cash App Loan Repayment — Step by Step
Step 1 — Check your due date
Banking tab → Borrow → View your active loan details.
Step 2 — Confirm your Cash App balance covers the amount
Add the original amount plus the 5% fee.
Step 3 — Let automatic repayment happen, or repay manually early
Banking → Borrow → Pay Early, if you want to settle it ahead of time.
Step 4 — Keep the repayment amount untouched until the due date
If repaying automatically, do not spend the funds you are setting aside.
Step 5 — Confirm repayment in your transaction history
Check that the deduction matches what you expected.
Cash App Loan Extension — Can You Get More Time?
People searching for a “cash app loan extension” are usually hoping for a way to push back their due date if they are not ready to repay. Here’s the honest answer.
There Is No Formal, User-Initiated Extension Option
Cash App Borrow does not currently offer a button or formal request process to extend your due date. The loan term is fixed at four weeks from acceptance.
What Actually Happens If You Cannot Repay on Time
- The late fee (1.25% weekly) begins accruing automatically
- Cash App may continue attempting collection from your balance or linked bank account
- This functions as a de facto extension, but at a cost, rather than a formal agreed extension
What to Do Instead of Hoping for an Extension
- Repay what you can manually, even partially, as soon as possible to reduce the outstanding balance
- Contact Cash App support directly through the app if you are facing genuine hardship — they may have options not advertised publicly
- Avoid borrowing again before resolving the current loan
Cash App Loan Statement — Where to Find Your Records
Cash App Borrow does not generate a traditional “loan statement” document the way a mortgage or auto loan might. Instead, your records live in two places:
Where to Find Your Loan Details
- Banking tab → Borrow — shows your current loan amount, fee, and due date while the loan is active
- Activity tab (transaction history) — shows the original loan deposit and the repayment deduction as line items, timestamped
If You Need Formal Documentation
If you need a record for budgeting, taxes, or any official purpose, screenshot the loan agreement at the time you accept it, and screenshot your transaction history showing the repayment. Cash App support can also be contacted through the app for a record of past Borrow activity if needed.
Cash App Loan Address — What Address Is Used and Why
The “address” question usually comes up in two different contexts, so let’s cover both clearly.
Your Address on File
The address associated with your cash app loan is the one tied to your verified Cash App account profile — the same address you used during identity verification (name, date of birth, SSN last four digits). This is what appears on any official communication or documentation related to your account.
The Lending Bank’s Address
Some loan agreements reference the address of the regulated partner bank that actually underwrites the loan. This information is disclosed directly within your specific loan agreement in the app — it can vary depending on which partner bank is associated with your account, so always refer to your in-app agreement rather than a generic address found online.
How to Borrow Money Instantly From Cash App — Step by Step
If your account already has access, here is the complete process.
Step 1 — Open Cash App and tap the Banking tab (house icon)
Step 2 — Scroll down to find “Borrow”
If you see it, you have access. If not, your account isn’t currently eligible.
Step 3 — Tap Borrow, then “Unlock” if prompted
Step 4 — Review your offer
Amount available, 5% fee, total repayment, and due date.
Step 5 — Select your amount using the slider, up to your maximum offer
Step 6 — Read the full loan agreement
Step 7 — Accept
Authenticate with your PIN or biometrics if prompted.
Step 8 — Funds appear in your Cash App balance instantly
How to Get $200, $300, $25, or $20 Fast
These specific dollar amounts come up constantly, so here’s a direct, honest answer for each.
How Do I Borrow $200 From Cash App?
If your available offer is $200 or higher, select $200 on the slider, review the $10 fee (5%), and accept. If your offer is below $200, you can only borrow up to your current maximum — there’s no way to manually request more.
How Can I Borrow $300 From Cash App?
Same process — only possible if your current offer is $300 or above. If not, consider whether a cash advance app like Dave or Earnin, which sometimes offer higher amounts to newer accounts, fits your timeline better.
How to Get $25 Instantly?
A $25 cash app loan is one of the easiest amounts to access if you have any Borrow eligibility at all, since most first-time offers start in the $20–$150 range. Select $25 on the slider; the fee is just $1.25.
How to Borrow $20 Instantly?
$20 is the minimum amount Cash App Borrow offers. If your account has Borrow access at all, $20 should be available even if your maximum is low.
How to Get 200 Dollars Fast (Without Cash App Borrow)
If Cash App Borrow isn’t available to you, other no-credit-check options include Dave (up to $500), Earnin (up to $300/day based on income), and Chime SpotMe (up to $200, fee-free with qualifying direct deposit).
Is It Hard to Borrow Money From Cash App?
It depends entirely on whether your account already has Borrow access.
If you have access: It is genuinely one of the easiest borrowing processes available — a few taps and instant funding.
If you do not have access: It can feel frustrating, because there’s no application form to fill out or appeal to make. Eligibility is generated automatically based on account history, primarily direct deposit activity and account age. Building that history over 60–90 days is the most reliable path.
Comparison Table — Cash App Loan vs Alternatives
| Option | Max Amount | Fee/Rate | Credit Check | Speed |
|---|---|---|---|---|
| Cash App Loan | $400 (up to $500 some accounts) | 5% flat | No | Instant |
| Dave | $500 | $1/month | No | Same-day |
| Earnin | Up to $300/day | Optional tip | No | 1–3 days |
| Chime SpotMe | $200 | Free | No | Instant |
| Personal loan | $1,000+ | 6–36% APR | Yes | 1–7 days |
| Payday loan | $100–$1,000 | 300%+ APR | Sometimes | Same-day |
Common Mistakes to Avoid
Mistake 1 — Assuming you can borrow $1,000
The realistic ceiling is $400–$500. Plan around the actual limit, not an inflated claim from an unverified source.
Mistake 2 — Spending your repayment money before the due date
Once you’ve set aside the repayment amount, treat it as already spent.
Mistake 3 — Expecting an extension
There is no formal extension process — only late fees if you miss the deadline.
Mistake 4 — Not reading the loan agreement’s specific bank and terms
Details like the underwriting bank can vary by account — always check your own agreement rather than relying on a generic online answer.
Mistake 5 — Treating it as a routine monthly tool
The 5% fee adds up if used every month. It’s designed for occasional short-term gaps, not recurring income shortfalls.
Pro Tips 2026 — Updated
Tip 1 — Set up direct deposit even partially to build the single strongest eligibility signal.
Tip 2 — Borrow below your maximum and repay early consistently to build toward a higher limit over time.
Tip 3 — Screenshot every loan agreement the moment you accept it, for your own records since no formal statement is issued.
Tip 4 — Compare the 5% fee against alternatives like Dave or Earnin before borrowing, especially for smaller amounts.
Tip 5 — Keep an emergency fund goal so the cash app loan stays a rare backup rather than a monthly habit.
FAQ Section
Q1. Can I borrow a loan from Cash App?
Yes, through the Cash App Borrow feature — but only if your account is eligible. Eligibility is based on account activity and direct deposit history, not a manual application.
Q2. How do I borrow $200 from Cash App?
If your available offer is $200 or more, select that amount on the slider in Banking → Borrow, review the 5% fee, and accept.
Q3. Can you borrow $1,000 from Cash App?
No. The realistic maximum reported is $400–$500, not $1,000.
Q4. How do I borrow $500 from Cash App?
Only possible if your account’s maximum offer reaches $500, which typically requires a strong account history and, in some cases, a paid subscription tier.
Q5. Will Cash App give me a loan?
Only if your account meets their internal eligibility criteria — mainly consistent direct deposit and account activity. There’s no guarantee for any individual account.
Q6. How to get $25 instantly?
If you have Borrow access, $25 is easily within the typical starting range ($20–$150) for most first-time users.
Q7. How can I borrow $300 from Cash App?
Same process as any amount — only available if your current maximum offer is $300 or higher.
Q8. How to borrow $20 instantly?
$20 is the minimum loan amount and is generally accessible to anyone with Borrow eligibility at all.
Q9. How do I borrow money instantly from Cash App?
Banking tab → Borrow → select amount → accept terms. Funds appear in your balance instantly if you’re eligible.
Q10. What is the limit on Cash App loan?
Most users see $20–$400; some higher-activity or subscriber accounts may see up to $500. There is no official guarantee of reaching the top of that range.
Q11. How to get 200 dollars fast?
Cash App Borrow if eligible; otherwise Dave, Earnin, or Chime SpotMe are reliable no-credit-check alternatives.
Q12. Is it hard to borrow money from Cash App?
It’s easy once you have access, but access itself depends on account history that can take 60–90 days to build.
Q13. How to get money on Cash App?
Through direct deposit, receiving payments from other users, selling stock or Bitcoin held in the app, or Cash App Borrow if eligible.
Q14. Can I borrow cash from an app?
Yes — Cash App, Dave, Earnin, Brigit, and MoneyLion are widely used no-credit-check cash advance apps, each with different limits and fee structures.
Conclusion & Action Steps
My $200 rent shortfall got solved with a few taps and a $7.50 fee — but only because I had unknowingly built the account history that made Cash App Borrow available to me months before I actually needed it.
That’s the real lesson behind every cash app loan question in this guide: the feature itself is simple once you have access. Getting access is the part that requires patience and consistent account activity, not a clever trick or a workaround.
Before borrowing, always compare the 5% fee with alternatives and only use Cash App Borrow for short-term emergencies. Check your eligibility today by opening Cash App and navigating to Banking → Borrow
Take action right now:
Step 1 — Open Cash App and check Banking → Borrow to see your current status
Step 2 — If eligible, review your exact fee and due date before accepting anything
Step 3 — If not eligible, set up direct deposit and use your Cash Card regularly for 60+ days
Step 4 — Screenshot any loan agreement you accept for your own records
Step 5 — Compare against Dave, Earnin, or Chime SpotMe if you need funds sooner
Step 6 — Review CFPB resources at consumerfinance.gov before relying on any short-term borrowing regularly